

You may be reading headlines and hearing talk about a potential housing bubble or a crash, but it’s important to understand that the data and expert opinions tell a different story. A recent survey from Pulsenomics asked over one hundred housing market experts and real estate economists if they believe the housing market is in a bubble. The results indicate most experts don’t think that’s the case (see graph below):
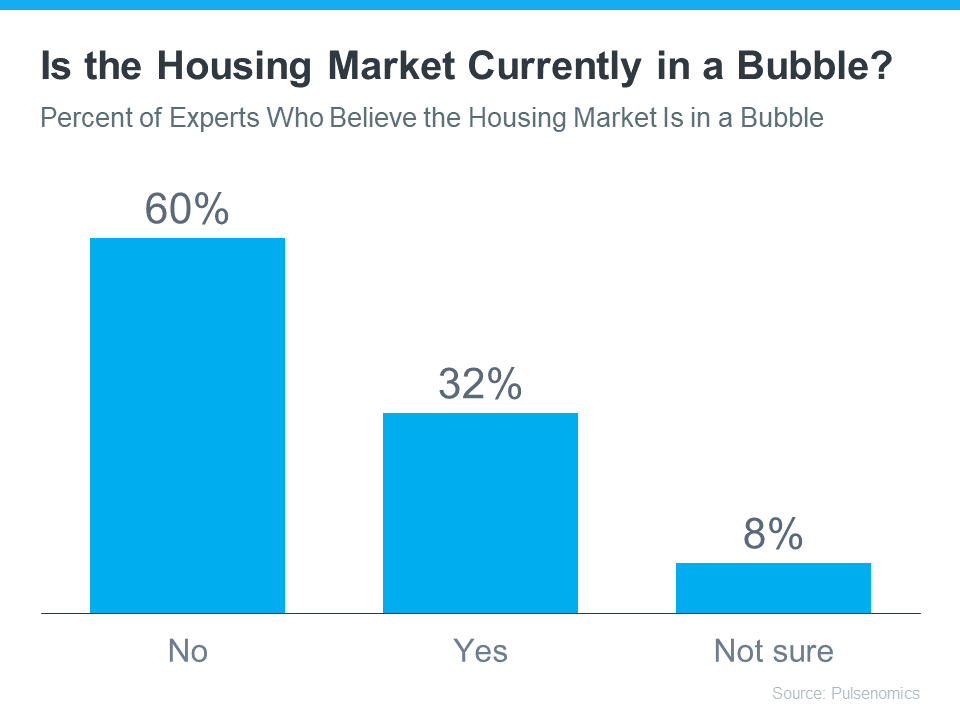 As the graph shows, a strong majority (60%) said the real estate market is not currently in a bubble. In the same survey, experts give the following reasons why this isn’t like 2008:
- The recent growth in home prices is because of demographics and low inventory
- Credit risks are low because underwriting and lending standards are sound
If you’re concerned a crash may be coming, here’s a deep dive into those two key factors that should help ease your concerns.
1. Low Housing Inventory Is Causing Home Prices To Rise
The supply of homes available for sale needed to sustain a normal real estate market is approximately six months. Anything more than that is an overabundance and will causes prices to depreciate. Anything less than that is a shortage and will lead to continued price appreciation.
As the graph below shows, there were too many homes for sale from 2007 to 2010 (many of which were short sales and foreclosures), and that caused prices to tumble. Today, there’s still a shortage of inventory, which is causing ongoing home price appreciation (see graph below):
 Inventory is nothing like the last time. Prices are rising because there’s a healthy demand for homeownership at the same time there’s a limited supply of homes for sale. Odeta Kushi, Deputy Chief Economist at First American, explains:
“The fundamentals driving house price growth in the U.S. remain intact. . . . The demand for homes continues to exceed the supply of homes for sale, which is keeping house price growth high.”
2. Mortgage Lending Standards Today Are Nothing Like the Last Time
During the housing bubble, it was much easier to get a mortgage than it is today. Here’s a graph showing the mortgage volume issued to purchasers with a credit score less than 620 during the housing boom, and the subsequent volume in the years after:
 This graph helps show one element of why mortgage standards are nothing like they were the last time. Purchasers who acquired a mortgage over the last decade are much more qualified than they were in the years leading up to the crash. Realtor.com notes:
“. . . Lenders are giving mortgages only to the most qualified borrowers. These buyers are less likely to wind up in foreclosure.”
Bottom Line
A majority of experts agree we’re not in a housing bubble. That’s because home price growth is backed by strong housing market fundamentals and lending standards are much tighter today. If you have questions, let’s connect to discuss why today’s housing market is nothing like 2008.

Chrysti Tovani is a Fair Oaks Real Estate Advisor, Transition Specialist, and the author of Downsizing with Intention. She helps homeowners sell long held homes, downsize with clarity, and navigate major life transitions with confidence and strategic guidance.
With decades of experience in real estate, mortgage, and title, Chrysti brings deep industry knowledge and thoughtful preparation to every transaction. Her approach blends strategic home marketing, skilled negotiation, and emotional intelligence, ensuring that each move is handled with both precision and care.
As the founder of I Love Fair Oaks, a hyperlocal media platform highlighting trusted businesses and community life in Fair Oaks, California, Chrysti has built an integrated authority ecosystem that connects real estate expertise with community leadership.
Her work centers on clarity, visibility, and long term legacy, helping clients move forward with confidence while strengthening the community she serves.


 The 2022 housing market has been defined by two key things: inflation and rapidly rising mortgage rates. And in many ways, it’s put the market into a reset position. As the Federal Reserve (the Fed) made moves this year to try to lower inflation, mortgage rates more than doubled – something that’s never happened before […]

 It turns out, millennials aren’t the renter generation after all. The 2022 Consumer Insights Report from Mynd says there’s a portion of millennial and Gen Z buyers who are pursuing homeownership as a way to build their wealth, but it may not be exactly the way previous generations have done it. The study explains how […]